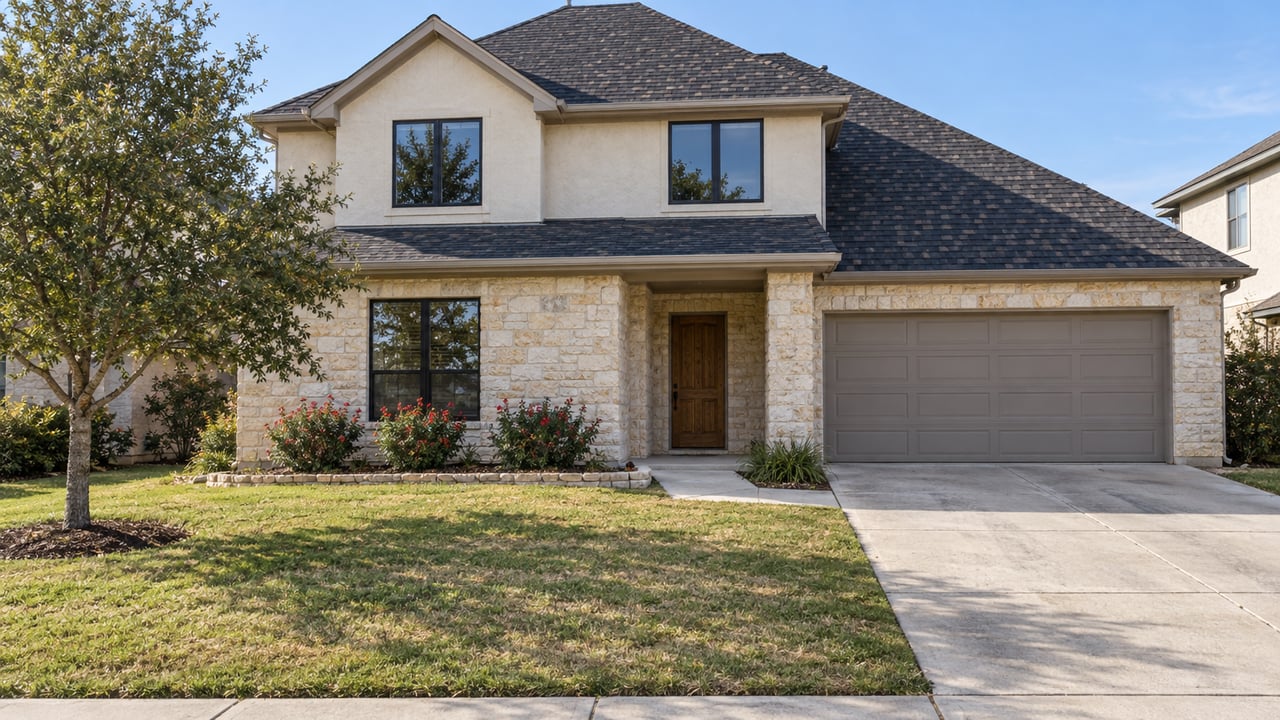
In Schertz, Is the Builder's Rate Competing With the Resale Price?
On Crosby Creek in Homestead, Coventry Homes has a move-in-ready four-bedroom, three-bath Dumont plan with 2,941 square feet. It's priced at $499,990, down from $556,523, with a "$56K off" tag next to the price. The same listing shows an estimated payment of $2,269 a month. A few streets over in the same community, Highland Homes' sales office at 4920 Childress Lane advertises rates "as low as 4.99%" on select quick move-in homes. In the week ending October 8, 2026, Freddie Mac's Primary Mortgage Market Survey put the national average 30-year fixed rate at 7.40%.
That leaves a gap of roughly 2.4 percentage points, and in dollars it's bigger than the $56,000 markdown. A Schertz resale home listed this fall is competing with the payment the builder can offer, so for buyers and sellers alike, the useful comparison is what each house costs per month and how long that monthly cost lasts.
This is our own illustration. It uses a $400,000 loan on a 30-year fixed mortgage and counts principal and interest only. It isn't a quote, and actual pricing depends on the lender and the borrower.
| Scenario on a $400,000 loan | Rate | Approx. monthly P&I | Monthly savings vs. market |
|---|---|---|---|
| Market average, week of Oct. 8, 2026 | 7.40% | about $2,770 | none |
| Seller cuts the price $16,000, so the loan drops to $384,000 | 7.40% | about $2,659 | about $111 |
| Seller puts the same $16,000 into about 4 discount points | about 6.40% | about $2,502 | about $268 |
| Builder's advertised rate on select homes | 4.99% | about $2,145 | about $625 |
The third row relies on a rule of thumb. Freddie Mac's explainer on discount points says one point, equal to 1% of the loan amount, can lower the rate by about 0.25 percentage point, and that the effect varies by lender. At 7.40%, a resale seller would have to take about $90,000 off the loan to match the 4.99% payment through price alone.
The same $16,000 lowers the payment more than twice as much when it goes toward the rate. John Burns Research and Consulting made this point in a 2023 analysis: a seller contribution of 4% of proceeds could cut a buyer's payment by 10%, while a 10% price cut lowers the price by 10%.
Most resale sellers will run into this limit. Each loan program caps how much an "interested party" can contribute, and the rules for what counts toward the cap differ by program.
Builders are subject to the same caps. Fannie Mae counts builders, developers, and their affiliates as interested parties. Using the rough Freddie Mac rule, a permanent drop from 7.40% to 4.99% would take about 9.6 points. That's more than the VA cap and more than the conventional cap for a buyer putting little down. The builder pages don't explain how each advertised rate is structured or who qualifies. A low headline rate on a few homes may be a temporary buydown, it may apply only to certain inventory, or it may be funded in ways the listing doesn't show.
This helps resale sellers. A builder's 4.99% may not last for the full 30 years, and a resale seller who understands the cap can put the allowed concession where it lowers the payment most.
The September 2026 numbers from the San Antonio Board of REALTORS® show where the region's discounting is happening. In its October 9 release, the San Antonio-area median price was $302,999, down about 2% from a year earlier. Homes averaged 88 days on the market, inventory reached 5.95 months, and homes closed at an average of 92.4% of their original list price. These are regional figures, not Schertz-only, but they show the pattern. On average, sellers gave up about 7.6% of their original asking price.
On a $400,000 home, 7.6% is about $30,400. Taken off the price, that saves a buyer around $210 a month at 7.40%. A smaller amount, kept within the program caps and spent on the rate, can save more, as the table shows.
Builders have shifted how they discount. In the National Association of Home Builders' September 2026 survey, 66% of builders were using sales incentives, while 38% cut prices, by an average of 6%. Builders lead with incentives and use price cuts as a second tool.
When we checked the builders' pages this month, several Schertz communities within a short drive of one another were actively building:
These price ranges cover much of the resale market. Nationally, the new-home median also sits below the existing-home median. NAHB put the second-quarter 2026 medians at $410,700 for new homes and $434,900 for existing homes.
Road projects will keep this part of town under construction for a while. Community Impact lists I-35 NEX Central as a $1.5 billion project scheduled through fall 2027, with FM 1103 expansion also underway. TxDOT expects the 5.6-mile FM 1518 rebuild between FM 78 and I-10, which adds a raised median, a shared-use path, and sidewalks, to be finished in 2028. Land is still moving through the pipeline as well. The city's October 7, 2026 Planning and Zoning packet includes a request to rezone about 21 undeveloped acres from single-family R-2 to R-5, with rental units as the proposed use. It's a request, not an approval.
A builder's estimated payment and a resale listing price aren't the same kind of number. These questions help put them on the same basis:
Can a resale seller offer a rate buydown? Yes. VA's guidance says the seller, the builder, the lender, or the borrower can fund a buydown, and the program caps above still apply.
Is there current Schertz-only market data? Not in a reliable, current form. The SABOR figures cited above cover the San Antonio area as a whole.
Does the $56K markdown mean the home's value dropped? The listing compares one asking price with an earlier one. It doesn't show an appraisal or a closed sale.
If you're thinking about listing a Schertz home this fall, or weighing a builder's quick move-in against a resale, M. Stagers Realty Partners can lay out both monthly payments side by side, show which concession cap applies to your buyer's loan, and help you decide where a seller credit lowers the payment most. Start Your Journey with a conversation about the numbers.
This article is general information, not legal, tax or financial advice. Consult a qualified professional about your situation.
November 5, 2026
October 29, 2026

October 25, 2026
Whether you're buying your first home or you've been through the process before, knowing what you can ask for helps you make a more informed decision.
Our mission is to provide an experience that stands above the industry standard and challenges the status quo of the basic real estate agent. We want you to trust us as valuable real estate advisors, worthy of handling one of your largest purchases, sales or investments.